
Kentucky restaurant insurance covers bourbon country’s hospitality boom — Louisville’s NuLu and bourbon-trail tourism, Lexington’s scene, and small-city kitchens statewide. Kentucky’s framework is operator-friendly: a statute that presumptively pins responsibility on the drinker rather than the server, comp loss costs on a 19-year decline, and a tourism engine that keeps hospitality demand climbing.
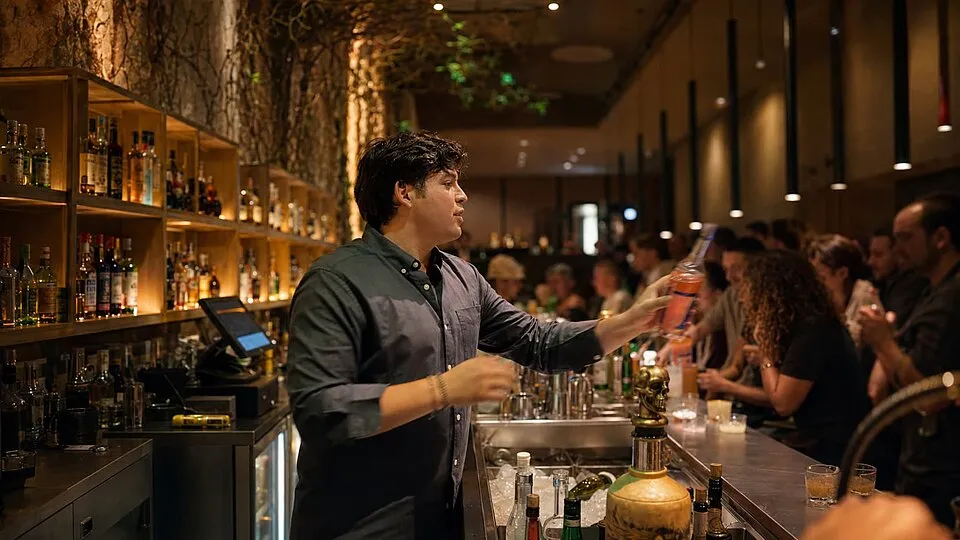
What restaurant insurance covers in Kentucky
The core program is the same coast to coast — what changes in Kentucky is the pricing, the liquor law, and the workers’ comp rules underneath it:
- General liability — customer injuries and foodborne-illness claims; $1M/$2M limits are the lease-and-vendor standard everywhere in Kentucky
- Liquor liability — Kentucky statute limits server liability — the law deems the drinker’s consumption, not the service, the proximate cause absent unusual circumstances
- Property & business interruption — build-out, equipment, and the income a closure interrupts
- Workers’ compensation — required from the first employee, with loss costs down 19 consecutive years (8.4% cut effective January 2025). Full state detail on our sister site: Kentucky workers’ comp guide.
- Spoilage & equipment breakdown — the refrigeration-failure claims every kitchen eventually files
Liquor liability in Kentucky: what the law means for your bar bill
Kentucky’s statute (KRS 413.241) declares the consumption of alcohol — not its service — the proximate cause of intoxication injuries, sharply limiting dram-shop-style claims against licensees except where a reasonable person should have known the patron was already intoxicated. It’s one of the more server-protective frameworks in the country, and Kentucky liquor liability prices accordingly. Bourbon-experience venues, distillery partnerships, and event pours still carry the exposures the statute leaves open — we write them to the actual law.
What Kentucky restaurants pay
Kentucky restaurants enjoy some of the friendliest total pricing we write: server-protective liquor law, 19 straight years of comp decreases, and modest real estate. For detailed workers’-comp rate context, see the Kentucky comp rates guide on our sister site.
Every kind of food business in Kentucky
From hot brown institutions to bourbon bars, the Kentucky formats we insure:
- Full-service restaurants
- Bars & taverns — liquor-led venues with dram-shop exposure
- Coffee shops & cafes
- Caterers — event and venue certificate specialists
- Fast casual & QSR
- Breweries & taprooms
- Pizzerias — delivery-driver coverage done right
- Fine dining — cellar valuation and revenue-real limits

Kentucky restaurant insurance FAQs
Does Kentucky have dram-shop liability?
Sharply limited — statute deems the drinker’s consumption the proximate cause, protecting servers except where intoxication was reasonably apparent. One of the country’s more operator-friendly frameworks, and liquor liability prices accordingly.
How much does restaurant insurance cost in Kentucky?
Your real number depends on payroll, operations, and carrier appetite — comparing several quotes side by side is the only way to see it.
Do bourbon-experience venues need special coverage?
Tasting flights, tours, and event pours carry the exposures the statute leaves open plus off-premises event questions — we structure bourbon-tourism operations to how they actually pour.
Is workers’ comp required for Kentucky restaurants?
From the first employee (agriculture is the main exemption) — with claims running through the state’s electronic LMS system and rates two decades into decline. Details on our sister site’s Kentucky guide.
Can you cover Derby-week surge staffing?
Pay-as-you-go comp prices Derby week as it happens instead of inflating the other fifty-one — the standard Louisville structure for hospitality’s biggest annual spike.
Get your Kentucky quotes: one application, multiple A-rated carriers that actively write Kentucky food businesses — start your quote or call 1-866-964-6660. More states: Indiana · Illinois · Michigan.
US Restaurant Insure connects food service business owners with Provident Financial Group. Insurance products are offered through Provident Financial Group, a licensed independent insurance agency, and are subject to underwriting approval, policy terms, conditions, and exclusions. Cost figures on this page are illustrative market ranges for planning purposes only — they are not quotes, offers of coverage, or guarantees of premium or savings. Coverage availability varies by state and carrier. Contact us at 1-866-964-6660 for a quote specific to your business.
Official Kentucky sources
- Kentucky Revised Statutes § 413.241 (dram shop liability)
- Kentucky Department of Alcoholic Beverage Control
- Kentucky Department of Workers' Claims: employer FAQ
- Kentucky Revised Statutes § 342.650 (workers' comp exemptions)
- 902 KAR 45:005 (Kentucky food code)
- Kentucky Revised Statutes § 304.39-110 (auto liability minimums)
State facts on this page are drawn from the statutes and agency pages above. Laws and agency rules change, so confirm current requirements with the agency before relying on them. This page is general information, not legal advice or a coverage opinion.
Restaurant insurance by business type in Kentucky
- Bar & Tavern Insurance in Kentucky
- Brewery & Taproom Insurance in Kentucky
- Coffee Shop & Cafe Insurance in Kentucky
- Catering Insurance in Kentucky
- Bakery Insurance in Kentucky
- Pizzeria Insurance in Kentucky
- Food Truck Insurance in Kentucky
- Ghost Kitchen Insurance in Kentucky
- Fast Casual Restaurant Insurance in Kentucky
- Fine Dining Restaurant Insurance in Kentucky
- Deli & Sandwich Shop Insurance in Kentucky
- Fast Food Restaurant Insurance in Kentucky
- Ice Cream Shop Insurance in Kentucky
- Food Vendor & Farmers Market Insurance in Kentucky
- Juice Bar & Smoothie Shop Insurance in Kentucky