
Brewery insurance covers three businesses wearing one logo: a manufacturer (brewing and packaging), a bar (the taproom), and often a distributor (kegs to accounts, cans to shelves). Each carries different classifications, different liability, and different property exposures — and the fastest-growing claim category in craft beverage is exactly where the three meet. Cideries, meaderies, and craft distilleries share the same architecture with their own wrinkles.
Coverage breweries and taprooms actually need
Property: tanks, production & stock
Brewhouses, fermenters, glycol systems, canning lines — plus beer itself as stock, including in-process batches. Tank collapse, contamination, and refrigeration failure need explicit coverage; a lost batch is a real property claim.
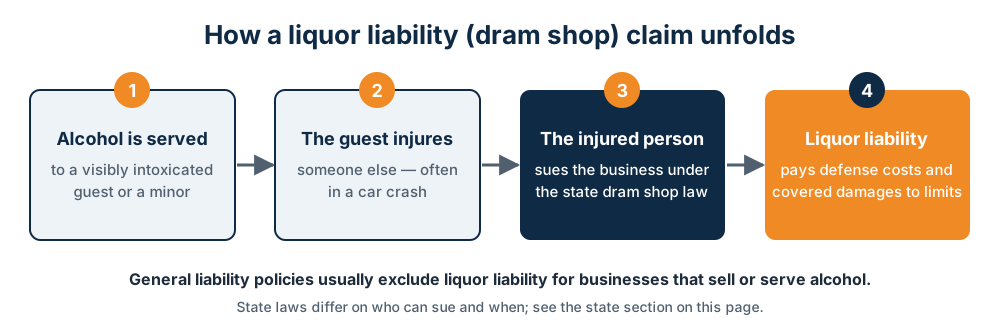
Liquor liability (taproom + events)
Taproom pours, festival bookings, and to-go sales all carry dram-shop exposure. Production-only breweries still need it the day they open a tasting room.
General & product liability
Taproom slips and tour injuries on the GL side; recalls, contamination, and bottle/can failures on the product side. Distribution multiplies product exposure across every shelf you reach.
Workers’ compensation
Production staff rate in manufacturing-type classes, taproom staff in hospitality classes — the payroll split matters, and blending them overprices the policy. Our sister agency’s food-and-beverage comp program handles the split correctly.
Equipment breakdown
Glycol chillers, boilers, and canning lines fail expensively — and take batches with them when they do. Breakdown coverage plus spoilage is the brewery’s production-continuity package.
What brewery & taproom insurance costs
Every restaurant is priced individually — alcohol share, payroll, square footage, location, claims history and the limits you choose all move the number. The fastest way to see yours is a side-by-side quote: Get Multiple Quotes within minutes.
Market ranges for planning, not quotes — every operation prices individually on location, revenue, payroll, and history. Compare policy terms, limits, deductibles, and premiums when reviewing quotes.
What goes wrong: the claims that hit breweries and taprooms
- Batch losses — contamination, temperature excursions, and tank failures; the claims brewers actually file
- Taproom liquor claims — a bar’s dram-shop exposure with a manufacturer attached to the same LLC
- Product recalls — distribution turns one bad batch into a many-state problem
- Production injuries — hot-side burns, CO2 exposure, keg handling, and confined-space tank work
- Festival and event liability — every pour off-premises needs coverage that traveled with it
The classification split that saves breweries money
The most common brewery overcharge is one classification covering two businesses: taproom servers rated as manufacturing payroll, or the whole operation carried on bar-type liability when production is most of the payroll. Splitting correctly — production classes for the brewhouse, hospitality classes for the front — routinely saves four figures. The second money-saver is stock valuation: beer priced as finished goods at your selling price, not ingredient cost, so a lost batch claim pays what the batch was worth. We write both correctly on every brewery account.
Brewery & Taproom insurance FAQs
What insurance does a brewery with a taproom need?
The full stack: production property (tanks, equipment, stock), liquor liability for the taproom, GL and product liability, workers’ comp with production/hospitality payroll split correctly, and equipment breakdown for glycol and packaging systems.
Does brewery insurance cover a contaminated batch?
With proper stock and contamination coverage, yes — including in-process batches valued at their real worth. It’s the most brewery-specific claim there is, and generic property forms handle it badly.
How much does brewery insurance cost?
Premiums are priced individually by each carrier; compare quotes side by side to see yours.
Do we need liquor liability if we only sell our own beer?
Yes — dram-shop exposure follows the pour, not the brand on the tap handle. Taprooms, festivals, and to-go sales all carry it.
Are brewery festival pours covered by our regular policy?
Only if the policy contemplates off-premises service — festival endorsements and event certificates (organizers require them) extend your coverage to where the beer actually goes.
Get covered right: one application, multiple A-rated carriers that actually want breweries and taprooms — start your quote. Related: Bar insurance · Fine dining insurance · Fast casual insurance · all coverages · what restaurant insurance costs.
US Restaurant Insure connects food service business owners with Provident Financial Group. Insurance products are offered through Provident Financial Group, a licensed independent insurance agency, and are subject to underwriting approval, policy terms, conditions, and exclusions. Cost figures on this page are illustrative market ranges for planning purposes only — they are not quotes, offers of coverage, or guarantees of premium or savings. Coverage availability varies by state and carrier. Contact us at 1-866-964-6660 for a quote specific to your business.
Brewery & Taproom Insurance by state
- Brewery & Taproom Insurance in New Jersey
- Brewery & Taproom Insurance in New York
- Brewery & Taproom Insurance in Connecticut
- Brewery & Taproom Insurance in Vermont
- Brewery & Taproom Insurance in Ohio
- Brewery & Taproom Insurance in Michigan
- Brewery & Taproom Insurance in Virginia
- Brewery & Taproom Insurance in Pennsylvania
- Brewery & Taproom Insurance in Delaware
- Brewery & Taproom Insurance in Maryland
- Brewery & Taproom Insurance in North Carolina
- Brewery & Taproom Insurance in South Carolina
- Brewery & Taproom Insurance in Georgia
- Brewery & Taproom Insurance in Florida
- Brewery & Taproom Insurance in Texas
- Brewery & Taproom Insurance in Kentucky
- Brewery & Taproom Insurance in Kansas
- Brewery & Taproom Insurance in California
- Brewery & Taproom Insurance in Indiana
- Brewery & Taproom Insurance in Arizona
- Brewery & Taproom Insurance in Washington, DC
- Brewery & Taproom Insurance in Massachusetts
- Brewery & Taproom Insurance in Nevada