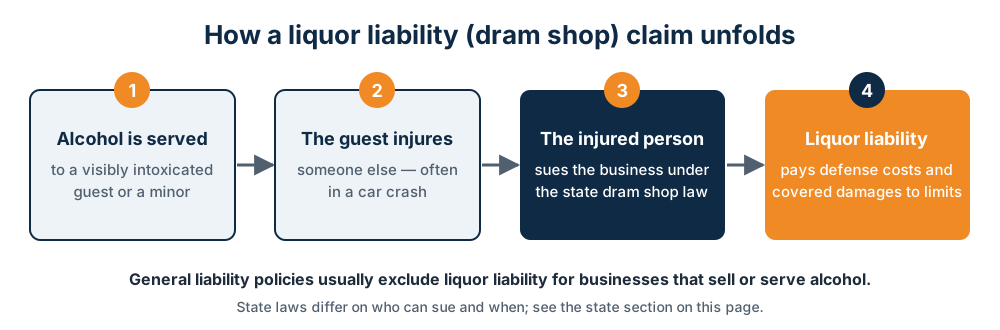
Virginia has no dram shop liability: in Williamson v. The Old Brogue, Inc. (1986), the Supreme Court of Virginia held that drinking the intoxicant, not furnishing it, is the proximate cause of a third party’s injury. Even so, most Virginia bars and restaurants carry liquor liability, because landlords and lenders require it, lawsuits still get filed, and fights and ABC violations remain real risks.
This page is for Virginia ABC licensees, from a Richmond cocktail bar to a Virginia Beach oceanfront restaurant, an Arlington sports bar or a Northern Virginia wedding caterer. It explains what Williamson does and doesn’t protect, and how to build coverage for the claims that still reach Virginia venues. For the statewide picture, see restaurant insurance in Virginia.
What Williamson v. The Old Brogue means for Virginia licensees
In Williamson v. The Old Brogue, Inc., 232 Va. 350, 350 S.E.2d 621 (1986), the court held that, apart from statute, drinking the intoxicant, not furnishing it, is the proximate cause of the injury, so vendors are not liable to third parties injured by intoxicated patrons. The court left any change to the General Assembly, so a future statute could alter the rule. The Virginia Alcoholic Beverage Control Authority (Virginia ABC) licenses and regulates retail alcohol sales, including mixed beverage restaurant licenses.
What Williamson doesn’t do: it doesn’t stop a plaintiff from filing suit and framing the case as negligent security, a premises defect or an employee’s own conduct, and someone still pays lawyers to get it dismissed. It doesn’t touch Virginia ABC enforcement against your license. And it doesn’t control events you cater in Maryland or DC, where different rules may apply.
| Exposure | Status in Virginia | What responds |
|---|---|---|
| Third-party dram shop claim | Not recognized (Williamson, 1986) | Liquor policy defense, subject to its terms |
| Social host civil liability | None specified in statute | Host liquor for private events |
| Fights and ejections | Ordinary negligence and intentional-tort claims | Assault and battery coverage |
| Slips, falls, premises | Ordinary premises liability | General liability |
| ABC violations | Suspension or civil penalty | Compliance and training records |
Social host liability in Virginia
No civil social-host liability is specified in Virginia statute (per NCSL), and Williamson declined to create common-law liability for tavern owners or social hosts. Liability for serving minors specifically is something we could not verify, so treat underage service as a serious risk regardless; it is also an ABC compliance problem. See liquor liability vs. host liquor liability.
Is liquor liability insurance required in Virginia?
We found no statutory liquor liability insurance or financial-responsibility requirement for on-premises licensees, and we treat that as unverified. The practical requirement is contractual: leases, franchise agreements, lenders, event venues and festival organizers routinely ask for a certificate naming them as additional insured.
Virginia ABC server training: MART, RSVP and STAP
Training is voluntary per Virginia ABC. ABC offers free MART (Managers’ Alcohol Responsibility Training) and RSVP (Responsible Sellers & Servers: Virginia’s Program), and certifies private courses through STAP. Virginia law lets ABC reduce a suspension or civil penalty for a retail licensee that shows it provided alcohol server/seller training to employees. In a no-dram-shop state, protecting the license is often where training pays off most, and underwriters still like to see it.
BYOB in Virginia: check before you pour
BYOB rules in Virginia are something we could not verify from official sources, so check with Virginia ABC before letting guests bring their own bottles or charging corkage. If you do allow it, ask how your general liability policy’s liquor exclusion treats BYOB service; see do BYOB restaurants need liquor liability.
Claim scenarios that still reach Virginia venues
- A Virginia Beach bar’s patron leaves drunk and injures a pedestrian. The family sues anyway, pleading negligent security; Williamson gives the bar a strong defense, but defense costs run until the case ends.
- Arlington sports bar staff restrain a guest during a playoff-night fight, and the guest alleges excessive force, an assault and battery claim.
- A Richmond restaurant is cited after a server sells to a minor during a compliance check; documented RSVP training can support a reduced penalty.
- A Northern Virginia caterer pours at a wedding in Maryland, where Virginia’s rule does not control the outcome.
Assault and battery and liquor exclusions: the real Virginia gap
With dram shop claims limited, fights and ejections become a larger share of your alcohol-related risk, so the assault and battery exclusion or sublimit is the line to scrutinize. Don’t drop liquor liability because of Williamson: general liability excludes alcohol-related claims for businesses that sell alcohol, so without a liquor policy no one may pay to defend that claim. See does liquor liability cover assault claims. A Virginia program typically includes:
- Liquor liability — defense for alcohol-related suits and certificates for leases.
- Assault and battery — the coverage to read most carefully.
- General liability — slips, food and premises claims.
- Host liquor — private events and staff parties.
- Umbrella — limits above GL and liquor (umbrella vs. excess).
- Workers’ comp — required with three or more regular employees (Virginia restaurant workers’ comp).
- Hired and non-owned auto — delivery and catering vehicles; auto minimums rose to 50/100/25 (in thousands of dollars) for policies effective Jan. 1, 2025 and later.
Setting limits without a dram shop threat
Lower dram shop exposure doesn’t mean any limit will do. Your landlord and lender set minimums, and an A&B sublimit far below the per-occurrence limit is where many policies run thin. The per-occurrence limit caps one incident; the aggregate caps every claim in the policy year. See per-occurrence vs. aggregate limits.
How alcohol sales shape your Virginia premium
Carriers still rate liquor liability on annual alcohol receipts. A family restaurant pouring wine with dinner rates very differently from a late-night bar where drinks are most of revenue. Hours, entertainment, occupancy, security staffing, prior claims and ABC violations also matter, and the state’s legal environment is one input underwriters consider. MART and RSVP training, ID scanning and incident logs are the practical levers.
Which Virginia businesses face which issues
- Bars — A&B claims and late-night crowds.
- Breweries — taproom events and lease-driven certificate demands.
- Caterers — events across state lines and venue contracts.
- Fine dining — wine service, private dining and ABC compliance.
Comparing carriers with an independent agency
Provident Financial Group sends one application to multiple carriers and compares limits, A&B terms and exclusions side by side. Once bound, you get live certificates of insurance to share with landlords, lenders and venues. Call (866) 964-6660.
Frequently asked questions
If Virginia has no dram shop law, why buy liquor liability?
Leases and lenders require it, plaintiffs still file suits that must be defended, and general liability excludes alcohol-related claims for businesses that sell alcohol.
Can a Virginia bar still be sued after a drunk-driving crash?
Yes, a suit can be filed. Williamson gives the bar a strong defense, but the policy’s defense coverage is what pays to get there.
Does RSVP or MART training help my license?
Yes. Virginia law lets ABC reduce a suspension or civil penalty for a licensee that shows it trained its staff.
Could Virginia adopt dram shop liability later?
Possibly. The Williamson court left any change to the General Assembly, so a statute could change the rule.
Compare your options. Get Multiple Quotes within minutes.
Official Virginia sources
State facts on this page are drawn from the statutes and agency pages above. Laws and agency rules change, so confirm current requirements with the agency before relying on them. This page is general information, not legal advice or a coverage opinion.
Related pages
- Bar insurance in Virginia
- Brewery insurance in Virginia
- Catering insurance in Virginia
- Fine dining insurance in Virginia
- Virginia restaurant insurance
- Restaurant insurance in Richmond
- Restaurant insurance in Virginia Beach