
Bars and taverns in Kansas typically need general liability, liquor liability, commercial property with hail and wind coverage, and workers’ compensation once gross annual payroll passes $20,000. Kansas has no dram shop statute, so liquor liability is driven mostly by landlord, lender and venue contracts and by fight and fall claims on your premises, but it remains one of the most important policies a Kansas bar can carry.
This page is written for owners of neighborhood taverns, sports bars, dive bars, cocktail lounges and live-music rooms across Kansas, from Wichita and Topeka to college-town bars in Lawrence and Manhattan, where most of the revenue comes across the bar rather than out of a kitchen. If you run a full-service restaurant with a bar, start with our Kansas restaurant insurance hub instead.
Kansas alcohol law and what it means for a tavern owner
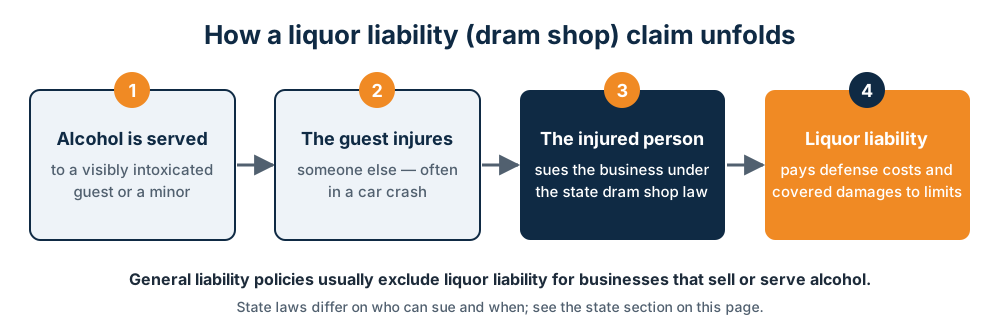
Kansas is unusual. The legislature repealed its old dram shop act in 1949, and in Ling v. Jan’s Liquors (1985) the Kansas Supreme Court refused to create liability for sellers who serve minors or intoxicated people, saying that choice belongs to the legislature. In Bland v. Scott (2005) the court again declined to create a third-party claim against suppliers of alcohol, including social hosts who served a minor.
That is good news, but it is not a free pass. The Kansas Department of Revenue’s Division of Alcoholic Beverage Control (ABC) can still impose administrative penalties on licensees, and patrons still sue bars over fights, falls, and injuries that happen on the property. Those lawsuits cost money to defend even when you win, which is exactly what a liquor liability and general liability program pays for.
A few other Kansas rules matter to bars. KDOR lists no statutory liability insurance requirement for on-premise licensees, but it does require a Liquor Drink Tax bond of at least $1,000, posted as cash, escrow or a surety bond. Server training is voluntary; ABC offers optional licensee education visits covering ID checks and underage drinking laws on request. Workers’ compensation is mandatory once your gross annual payroll exceeds $20,000, which nearly every staffed bar will hit. See our Kansas liquor liability guide for more detail.
How a Saturday night at a Kansas bar becomes an insurance claim
The claims we see at taverns rarely start with the alcohol itself. They start with what happens after a few rounds:
- A shoving match near the pool tables spills onto the patio, a patron fractures his cheekbone, and his attorney claims your doorman escalated it. Whether your policy includes assault and battery coverage decides whether a carrier defends you.
- Melted ice behind a crowded rail on a game-day afternoon puts a guest on the floor with a broken wrist.
- A spring hailstorm shatters your front windows and destroys the lighted sign, and the bar stays dark for a week while glass is replaced.
- Your walk-in cooler compressor dies on a holiday weekend and several days of kegged and bottled inventory warms up.
- A bartender slices a palm on a broken pint glass and needs stitches and two weeks off, a workers’ comp claim.
Insurance checklist for Kansas bars and taverns
- Liquor liability — defends alcohol-related injury claims and satisfies the lease and lender clauses most Kansas bar landlords include.
- Assault and battery coverage — many bar policies exclude fights or cap them with a sublimit; confirm yours covers them.
- General liability — slip-and-fall, trip, and guest-injury claims that have nothing to do with alcohol.
- Commercial property — building (if you own it), bar fixtures, coolers, TVs, sound systems, and signs against fire, wind and hail.
- Business income — replaces lost revenue and pays rent and payroll while storm or fire repairs keep you closed.
- Equipment breakdown and spoilage — walk-in coolers, draft systems, ice machines, and the inventory inside them.
- Workers’ compensation — required above the Kansas payroll threshold; covers cuts, burns, and back injuries from hauling kegs.
- Umbrella liability — extra limits above liquor and general liability, often required by landlords of larger venues.
What drives premium for a Kansas tavern
Underwriters price a bar on the share of revenue that comes from alcohol, hours (a midnight close rates very differently from a 2 a.m. close), capacity, entertainment such as live bands or dancing, whether you employ security staff, and your prior claims. Property pricing adds building age, construction, fire protection, and your county’s hail and wind history.
You can improve how carriers see you: use ID scanners, keep camera footage for at least a few weeks, log every incident in writing, request an ABC licensee education visit and document staff training, and write a clear cut-off policy. On the property side, a higher wind and hail deductible can help if your building can absorb it.
Quoting a Kansas bar with an independent agency
Provident Financial Group is an independent agency, so one application lets us compare multiple carriers side by side, including markets comfortable with late hours and entertainment. Once you bind, we issue certificates of insurance you can send to your landlord, lender, or event partners the same day. Call (866) 964-6660 or start online.
Frequently asked questions
Can a Kansas bar be sued if a customer drives drunk and hurts someone?
Kansas courts have refused to create dram shop liability, so a direct claim against the bar faces a steep legal hurdle. Plaintiffs still try, and defense costs are real, which is one reason liquor liability coverage remains worthwhile.
Does Kansas require bars to carry liquor liability insurance?
Not by statute. KDOR requires a Liquor Drink Tax bond of at least $1,000 for on-premise licensees, but liability insurance is usually required by your lease, lender, or event contracts instead.
Is server training mandatory for Kansas bartenders?
No statewide server-training mandate was found. ABC offers voluntary licensee education visits, and documented training can help your application with carriers.
Do fights inside my bar fall under liquor liability?
It depends on the policy wording. Many bar policies exclude assault and battery or limit it, so ask for that coverage by name when you compare quotes.
Want to see how carriers price your Kansas tavern? Get Multiple Quotes within minutes.